How Parametric Climate Insurance Works: A Practical Guide for Businesses and MSMEs
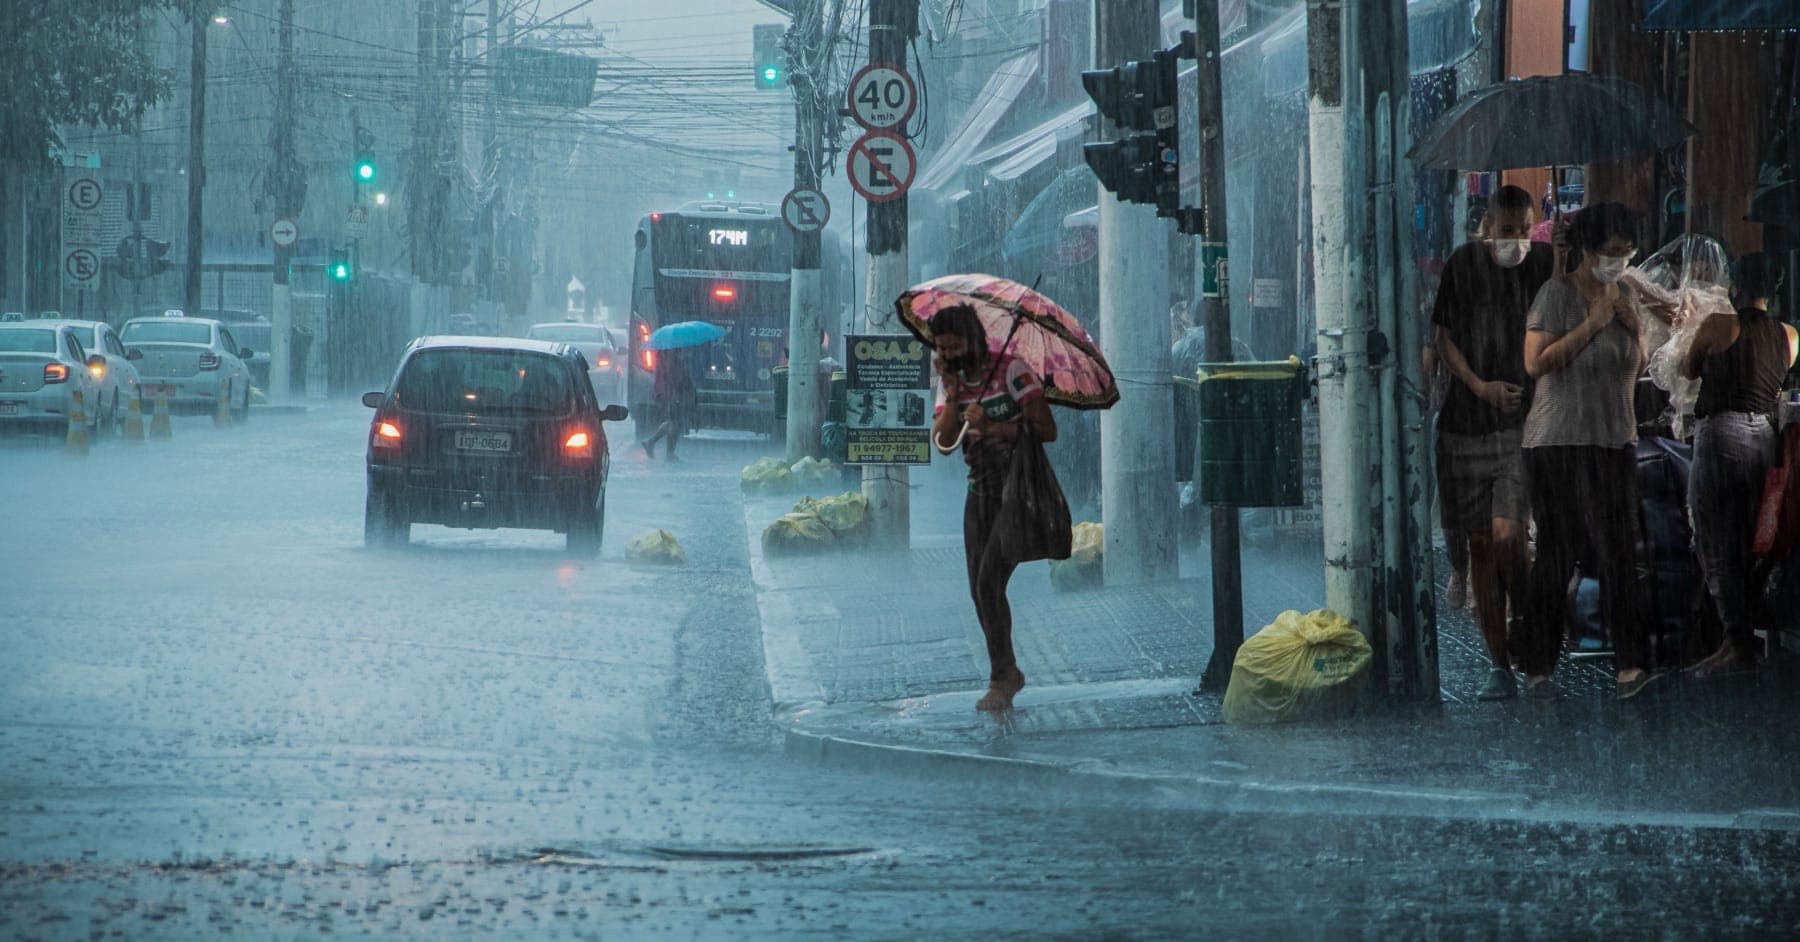
India experienced extreme weather on 331 out of 334 days in 2025 — a figure from the Centre for Science and Environment's Climate India 2025 report. For businesses and MSMEs, this is not an abstract statistic; it reflects a real and growing operational risk.
Floods, heatwaves, and unseasonal rain are now near-daily business risks. Most small businesses have no financial shield when the weather shuts them down. Parametric climate insurance is one tool that can change that.
Parametric climate insurance pays businesses fast based on weather data, not damage surveys. Learn how it works and what it covers for Indian MSMEs.
Written byAnkur IndrakushFounder & CPTO
The problem: extreme weather is now an everyday business risk
India has over 63 million MSME units employing more than 110 million people. These businesses are among the most exposed to weather extremes — they operate with thin margins and little financial buffer.
When Cyclone Michaung hit Tamil Nadu in December 2023, it affected 4,800 MSME units across 24 industrial estates, with losses of at least USD 360 million. In 2025, climate-related disasters cost India an estimated USD 12 billion.
Traditional insurance was never designed for this pace of disruption. Assessors take weeks to visit a site after a weather event, paperwork stretches into months, and cash flow is already broken — pushing MSMEs into debt.
What is parametric climate insurance?
Parametric climate insurance pays out based on a measurable event. Unlike traditional insurance, there is no need for a physical inspection of your losses. The trigger is a number, such as:
- rainfall exceeding 250 mm in 24 hours,
- wind speeds above 90 km/h, or
- temperatures crossing 45°C.
Think of it like a smoke detector. A smoke detector does not wait for the fire brigade to confirm a fire — it goes off when smoke crosses a threshold. Parametric insurance works the same way: when the weather event exceeds a pre-agreed level, the payout is released automatically.
The data comes from independent sources such as the India Meteorological Department (IMD), satellite readings, or weather station networks. There is no claim to file and no surveyor to wait for.
How it works for an Indian business: an illustrative scenario
Consider a textile unit in Surat, which faces a high risk of flooding during the monsoon. The owner takes a parametric policy with this trigger: if rainfall at the Surat IMD weather station exceeds 300 mm in any 48-hour period, the policy pays out ₹5 lakh within 72 hours.
In August 2025, rainfall in Surat crosses 320 mm over two days. IMD data confirms the trigger, which the insurer's system reads automatically. Within three days, the payment arrives in the owner's account — no claim form, assessor visit, or settlement negotiation. The business uses that money to repair machinery, pay workers, or cover lost orders while operations resume.
This is an illustrative scenario to explain the mechanism. Actual policy terms vary by insurer and product.
Real pilots are already running in India. Nagaland received its first parametric payout for rainfall-triggered flooding under a policy from SBI General Insurance, with Munich Re as reinsurer.
What this means in practice
Speed is the differentiating factor. Traditional business interruption insurance can take weeks to settle; parametric payouts arrive in days — even hours — after the trigger is confirmed.
This matters because weather damage is rarely just physical. The real cost is downtime: missed orders, broken supply chains, workers sent home. Fast cash flow lets businesses restart before losses compound.
Three practical outcomes from a well-designed parametric policy:
- Liquidity within days of a covered event, not months.
- No paperwork, no loss surveys, no adjuster visits.
- Predictable cover, since the trigger and payout are fixed in the contract upfront.
Businesses can stack parametric cover on top of traditional property insurance — it fills the gap between the event and the traditional payout rather than replacing it.
Traditional vs. parametric business insurance
| Feature | Traditional Business Insurance | Parametric Climate Insurance |
|---|---|---|
| Payout trigger | Verified physical loss after assessment | Pre-agreed weather data threshold |
| Average payout time | Weeks to months | ~24 hours of meeting trigger conditions |
| Claims process | Surveyor visit, documentation, negotiation | Automatic; no filing required |
| Basis of cover | Actual financial loss incurred | Occurrence of the specified event |
| Basis risk | Low (loss is directly assessed) | Exists (trigger may not match actual loss) |
What parametric climate insurance does not cover
The main limitation is basis risk — the gap between what the trigger says and what actually happened to your business. If a policy pays out above 300 mm of rainfall but the nearest IMD station records 285 mm while your factory floods, the trigger is not met and the policy does not respond.
This is not unique to India; the World Economic Forum's January 2025 analysis identifies basis risk as the key structural challenge in any parametric product. The responsibility falls on the buyer to understand which triggers matter and set them accordingly — which calls for a thorough business climate risk assessment.
Where this leaves Indian businesses today
Extreme weather is no longer a rare disruption; it is a recurring operating condition. Parametric climate insurance offers speed and certainty that traditional insurance cannot. It does not remove risk or replace good risk management — it provides fast, predictable liquidity at the moment businesses need it most.
IRDAI has signalled the need for broader climate risk cover under its 'Insurance for All by 2047' framework. As the category matures, businesses that understand how parametric cover works will be better positioned to manage climate risk.
00 Comments
Start the conversation
Be the first reader to share a thoughtful response.
Leave a Reply
Your email address will not be published. All comments are reviewed before appearing publicly.