Same Rainfall, Same Payout: How Index-Based Insurance Removes the Guesswork from Crop Protection
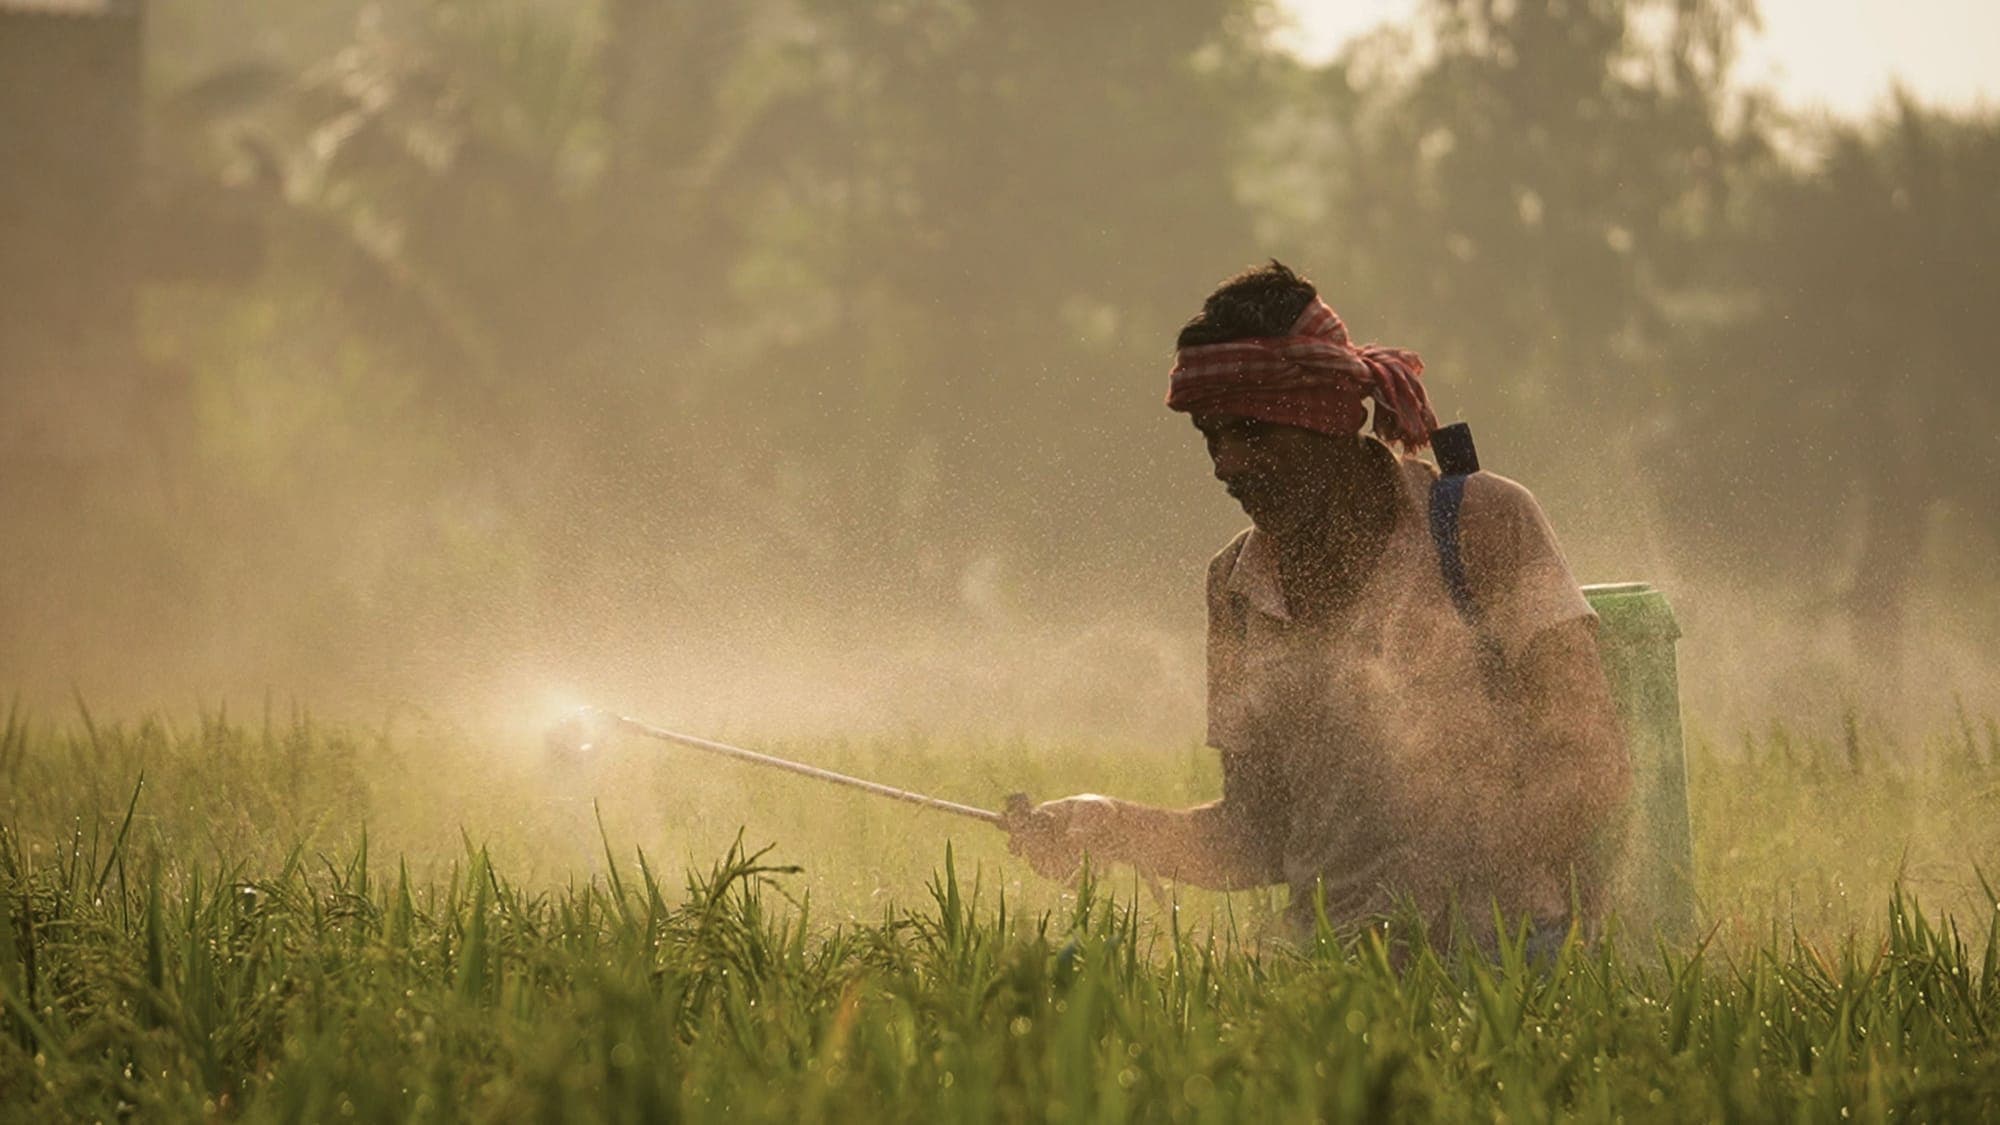
In 2025, over 1.58 lakh hectares of cropland were damaged across 13 Indian states between April and July due to floods. Maharashtra alone lost more than 90,000 hectares. Farmers had to wait for months before receiving financial relief.
Rural India's heavy dependence on seasonal, rainfed agriculture increases the severity of the situation. For a family whose income depends on one crop per season, a single failed harvest can take years to recover from.
Index-based crop insurance uses measurable weather triggers to deliver faster, predictable payouts, helping farmers manage climate-driven crop losses without lengthy damage assessments.
Written byReecha SinhaVice President
Why Traditional Crop Insurance Keeps Farmers Waiting
India's PMFBY scheme has paid out over ₹1.83 lakh crore to farmers since its 2016 launch. While this is a significant achievement that demonstrates the scale of agricultural insurance support, the journey from crop loss to payment can still be lengthy.
Under PMFBY, a claim generally depends on crop-cutting experiments and yield assessment. Trained workers collect field-level data, states compile and submit the results, and insurers process claims based on the assessed loss. In practice, Kharif 2024 claims had not been fully settled as of February 2025, more than four months after harvest.
For a farmer already carrying debt from that season's inputs, the delay can mean:
- Taking fresh loans to survive the gap
- Selling cattle or assets at distress prices
- Missing the planting window for the next season
The delay is not necessarily about intent. It is a consequence of the underlying model. Yield-based insurance requires physical or statistical measurement of agricultural losses, which takes time.
Rainfall and Crop Stress Across Selected States, Kharif 2025
| State / Region | Monsoon Rainfall Status (Jun–Aug 2025) | Agricultural Impact |
|---|---|---|
| Maharashtra (Marathwada) | Deficient in parts (30–70% below normal) | Soybean and cotton stress; 90,000+ hectares affected |
| Bihar | 30–70% below normal in parts | Crop stress; drought-like conditions |
| Punjab | Below normal in parts | Reduced soil moisture; paddy risk |
| Southern India | Above normal | Better reservoir levels; stronger sowing |
| India Overall | 3% above Long Period Average | Highly uneven across districts |
Source: India Meteorological Department (IMD), CEED India analysis, September 2025
The national averages can be misleading. While India's aggregate rainfall in 2025 was slightly above normal, specific districts faced severe deficits during the same season. This spatial unevenness is one of the reasons location-specific index-based crop insurance is becoming increasingly relevant.
What Is Index-Based Crop Insurance?
Index-based insurance removes the need to assess every individual field after a weather event. Instead of measuring the actual loss on a farm, it uses an observable and independently verifiable parameter, known as an index.
In one common structure, that index is rainfall. A threshold is established before the season begins. If rainfall recorded by an approved weather data source falls below that threshold during a defined crop-growth period, a payout is triggered for enrolled policyholders in the covered area.
Think of it as a shared weather signal. When the data crosses the agreed threshold, the payout mechanism activates. The farmer does not need to prove the extent of crop damage through a post-event survey.
This approach is also described as parametric insurance for agriculture or weather-triggered insurance. The core principle is the same: the payout is linked to an objectively measured parameter rather than a conventional loss assessment.
How It Works in Practice: An Illustrative Example
Consider a soybean farmer in Amravati, a district in Vidarbha regularly exposed to erratic monsoons. Under an index-based parametric insurance for agriculture product:
- Before Kharif, a rainfall threshold is established. For example, if cumulative rainfall from June 15 to August 31 falls below 350mm according to the policy's specified weather data source, a payout is triggered.
- The farmer pays a premium at enrolment. The payout amount per hectare is fixed and known in advance.
- If the recorded rainfall falls below the specified threshold, the payout is processed according to the policy terms. No individual field inspection is required to establish the trigger.
Private insurance operators already offer parametric products linked to rainfall and other weather variables in India.
The key distinction from yield-based schemes is speed. Because the predefined index provides the trigger, the process does not have to wait for individual crop-loss assessments before determining whether the parametric condition has been met.
What Changes for a Farmer With This Cover
Three outcomes can change when weather-triggered insurance is added to a farmer's risk-management strategy:
- Speed: When the weather trigger is met, payment does not need to wait for state-level yield data or an individual field assessment. This can provide liquidity when a farmer needs cash for the next planting season.
- Certainty: The trigger conditions and payout structure are established before the season begins. Farmers can understand what weather conditions activate the cover and what payout they can expect under the policy.
- Simplicity: There is no conventional post-event claim assessment for the parametric trigger. For farmers in remote areas far from insurance offices, this can significantly reduce administrative friction.
The Limitation Every Farmer Must Understand
Index-based insurance is faster and simpler, but it comes with a known limitation called basis risk.
Basis risk is the gap between what the selected index records and what actually happens on an individual farm.
For example, suppose the relevant weather data records 380mm of rainfall during the insured Kharif period, while the policy threshold is 350mm. The threshold is not crossed, so no payout is triggered. But the farmer's particular field, located within the wider coverage area, may have received only 290mm because of localised rainfall variation, resulting in crop stress or failure.
The reverse can also occur. The weather index may fall below the threshold and trigger a payout even though a particular farm received adequate rainfall and experienced limited crop damage.
This is why the design of the index matters. Farmers should check:
- Which weather station, satellite dataset, or other data source determines the trigger
- How close the data source is to the insured location
- Which crop-growth period is covered
- What rainfall or temperature thresholds apply
- How much the policy pays when the trigger is reached
- Whether multiple trigger levels provide progressively higher payouts
Index-based crop insurance can also be combined with other agricultural risk-management tools to provide broader financial protection.
Wrapping Up
Index-based insurance does not remove climate risk. It changes how quickly and predictably a farmer can respond to it.
The payout depends on a predefined, measurable trigger rather than the time required to complete a traditional loss assessment. As India's weather-data infrastructure expands and increasingly granular climate information becomes available, index-based products have the potential to become more responsive to local agricultural conditions.
For farming families, the broader shift is important: moving from waiting for losses to be measured after a crisis toward having a predefined financial response when a climate trigger occurs.
Want to Protect Your Crops This Season?
Find out whether index-based insurance is available for your crop and district. Speak with insurers or authorised distribution channels to understand the available parametric insurance for agriculture products, their weather triggers, payout structures, exclusions, and coverage area.
00 Comments
Start the conversation
Be the first reader to share a thoughtful response.
Leave a Reply
Your email address will not be published. All comments are reviewed before appearing publicly.