From Climate Risk to Climate Resilience Solutions: How Parametric Insurance Is Changing Protection for Emerging Markets
Climate-related disasters cost India an estimated $12 billion in 2025 alone. Yet across emerging markets, including India, insurance covers only a small fraction of those losses. Across Asia, the gap between what climate events cost and what insurance pays out remains stubbornly wide.
More than 50% of farmers lost close to half their standing crops due to extreme weather events, according to the State of Marginal Farmers of India 2024, which studied 6,615 marginal farmers.
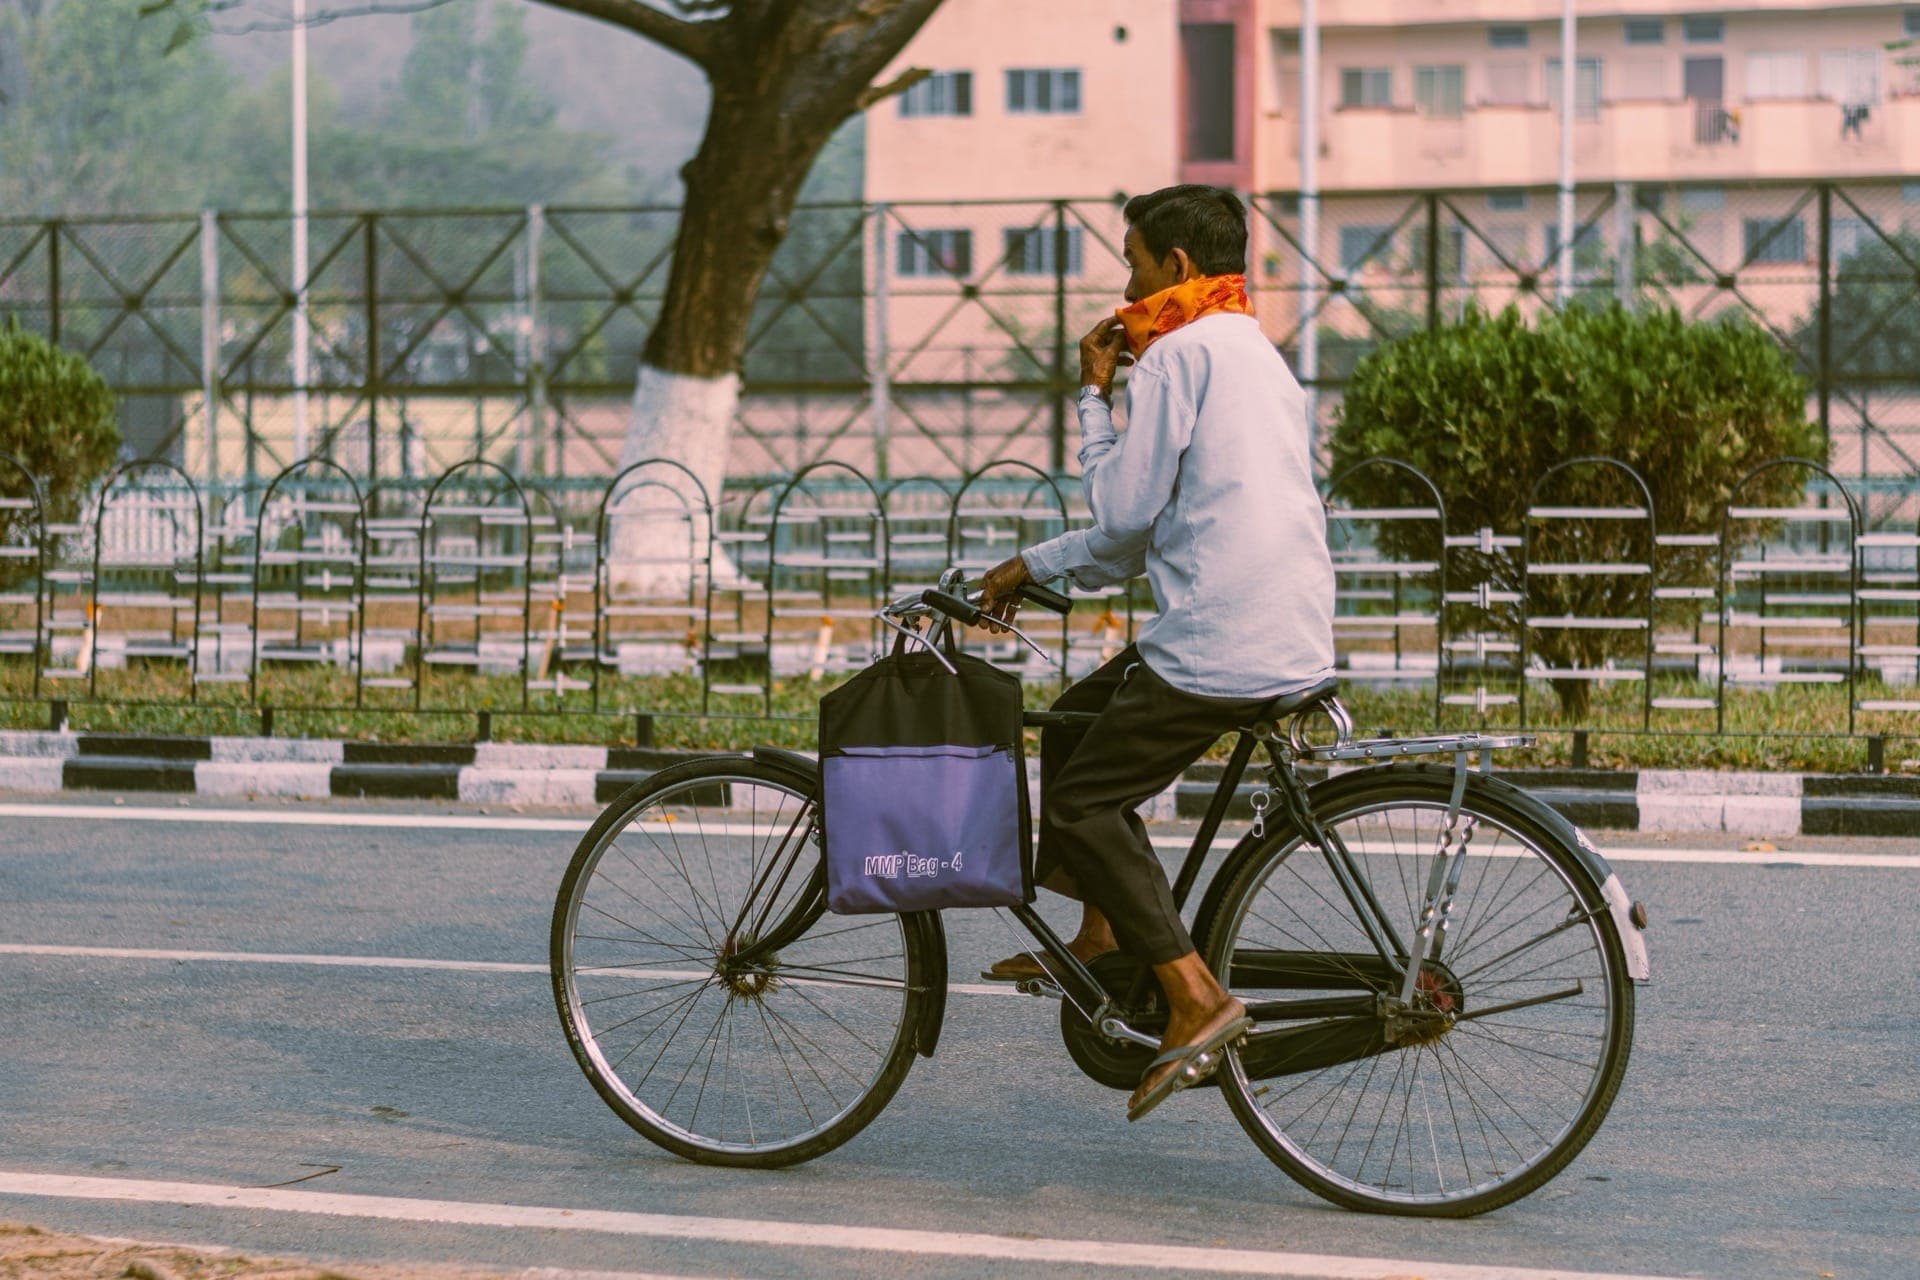
Gig workers face a similar problem. Heavy rain can mean fewer delivery hours. Extreme heat can make outdoor work unsafe. A climate event that lasts only a few days can translate into an immediate income shock for someone who depends on daily earnings.
India recorded 122 extreme weather events during the monsoon of 2025.
For farmers and gig workers, the climate protection gap is not simply a statistic. It can mean a lost season, a missed week's income, or taking on expensive debt to recover.
Parametric insurance is reshaping climate protection in emerging markets by delivering faster, simpler payouts to farmers and workers affected by extreme weather.
Written byAnupam ShreyFounder & CEO
The Problem: Who Bears the Cost of Climate Shocks?
India ranks sixth globally in climate vulnerability and has experienced hundreds of extreme weather events over the past three decades.
Between 2015 and 2021, India lost 33.9 million hectares of crops to excess rain. An additional 35 million hectares were affected by drought.
These losses do not fall evenly across the economy. Smallholder farmers and informal workers often have the least financial capacity to absorb them.
Gig workers face the same structural vulnerability. Extreme heat can significantly reduce working hours and daily earnings. Workers who continue working through dangerous heat and rainfall can also face health and safety risks.
This creates a fundamental problem:
The people most exposed to climate shocks are often the people least equipped to absorb the financial consequences.
Traditional insurance has helped close part of this gap, but its structure can make it difficult to serve low-income and informal workers at scale. Claims may require documentation, loss assessment, surveyor visits, and processing time.
For someone who needs money immediately after a climate shock, a payout received weeks later may not provide enough protection.
This is why microinsurance for climate shocks is becoming increasingly important.
How Climate Resilience Financing Solutions Bridge the Gap
Parametric insurance is one of the most practical climate resilience solutions emerging for climate-exposed communities.
Instead of paying based on an assessment of the actual damage, parametric insurance pays when a predefined, objectively measurable trigger is breached.
The basic mechanism is simple:
If the defined weather condition occurs, the predefined payout is triggered.
There is no need to determine exactly how much damage occurred before the payout can be processed.
The trigger can be based on variables such as:
- Rainfall
- Temperature
- Wind speed
- Humidity
- Flood levels
- Other objectively measurable weather or environmental indicators
The underlying data can come from sources such as meteorological stations, satellite observations, or other validated weather datasets.
For example, an illustrative policy might define a rainfall trigger:
If cumulative rainfall during June falls below 55 mm in the insured location, the policy pays ₹6,000.
The weather either crosses the agreed threshold or it does not.
For microinsurance for climate shocks, this simplicity is particularly important. Products designed for low-income workers, farmers, and informal businesses need to minimise paperwork and make protection understandable and accessible.
How Parametric Insurance Works in Practice
Let's consider a farmer in Vidarbha, Maharashtra, growing soybean.
A drought protection product could use rainfall data for the farmer's insured location. Before the policy begins, the insurer and customer agree on:
- The weather variable being monitored
- The location or measurement area
- The trigger threshold
- The payout amount
- The policy period
If rainfall during the specified period falls below the agreed threshold, the policy can trigger a predetermined payout.
The farmer does not need to prove the exact value of crop damage for the parametric trigger itself.
This approach has also been demonstrated through large-scale protection for informal workers.
Under SEWA's parametric microinsurance programme, which covers informal workers across multiple Indian states, heat-related triggers have been used to provide payouts when temperatures cross predefined thresholds. In 2025, the programme covered 225,000 members across seven states, with total payouts exceeding ₹2.3 crore during the heat season.
For gig workers, the same principle can be applied to income disruption caused by extreme heat or rainfall.
An illustrative heat-linked product for delivery workers could trigger when the daily maximum temperature exceeds a predefined threshold for a specified number of consecutive days.
Each enrolled worker would receive a predetermined payout without having to submit a conventional claim.
The underlying principle remains the same:
Measure the climate event. Trigger the protection. Deliver the payout.
What Changes for Farmers and Workers When This Exists?
The most important change is speed.
Parametric insurance can allow payouts to be processed rapidly after a verified trigger event. Traditional insurance often requires a damage assessment before the final payout can be determined.
For a family that has just lost a crop or missed several days of income, the difference between receiving support in a few days and waiting several weeks can be significant.
Climate insurance for emerging markets also changes three important dimensions of protection:
1. Certainty
The payout amount is established before the policy begins. The insured knows what they can expect if the trigger is breached.
2. Simplicity
The customer does not need to navigate a conventional damage-assessment process for the parametric trigger. This can make protection easier to understand and administer.
3. Accessibility
Digitally distributed parametric products can potentially make low-ticket protection more practical for farmers, informal workers, and other underserved populations.
Parametric Insurance Payout Speed: A Clear Comparison
Parametric insurance is structurally different from traditional indemnity insurance. The following comparison illustrates how the mechanisms can differ:
| Type of Cover | Trigger | Typical Payout Timeline |
|---|---|---|
| Traditional crop insurance | Assessed crop loss | Dependent on loss assessment and claim processing |
| Parametric heat insurance | Temperature crosses a predefined threshold for a specified duration | Potentially within days of trigger verification |
| Parametric insurance — illustrative scenario | Rainfall or temperature crosses an agreed threshold | Potentially 1–3 days, depending on product design and verification |
| Government disaster relief | Disaster formally declared and eligibility established | Can take weeks or longer |
Table 1: Illustrative comparison of insurance and climate-response mechanisms. Actual payout timelines vary by product, insurer, trigger design, and claims infrastructure.
Where Parametric Insurance Falls Short
Parametric insurance is a powerful climate resilience financing solution, but it is not a perfect substitute for traditional insurance or broader social protection.
The most important limitation is basis risk.
Basis risk occurs when the parametric trigger does not perfectly represent the actual loss experienced by the insured.
For example, imagine a rainfall-based policy linked to a weather station serving a particular area. The station records 60 mm of rainfall, so the policy does not trigger. However, a farmer's field may have received only 25 mm because of localised rainfall variation.
The farmer could experience crop stress without receiving a parametric payout.
This makes trigger design and data quality critical.
Other factors to consider include:
- Fixed payouts: The payout is agreed in advance and may not fully compensate for a very large loss.
- Product availability: Many parametric products in India remain relatively new and may be distributed through specific partnerships, groups, cooperatives, employers, or other channels.
- Changing climate patterns: Products based heavily on historical data need to account for changing weather patterns and evolving risk.
- Data quality: The accuracy, spatial resolution, frequency, and reliability of the underlying data directly affect trigger performance.
- Awareness: Many farmers and informal workers are still unfamiliar with parametric insurance and how it differs from conventional insurance.
The objective, therefore, should not be to position parametric insurance as a replacement for every form of protection.
It works best as one layer within a broader climate resilience solution.
From Insurance Product to Climate Resilience Infrastructure
The larger opportunity is not simply selling another insurance policy.
Parametric insurance can become part of a broader resilience infrastructure connecting:
Climate data → Risk assessment → Insurance trigger → Automated payout → Financial recovery
This changes the role of insurance from a product that responds after damage has been assessed to a mechanism that can provide liquidity when a measurable climate shock occurs.
For emerging markets, this distinction matters.
A farmer may need cash to purchase seeds after a failed crop cycle. A gig worker may need to replace several days of lost income. A small business may need working capital after a flood disrupts operations.
In each case, the value of insurance is not only the amount paid.
It is how quickly that money reaches the person who needs it.
This is where climate intelligence, digital distribution, and parametric insurance can work together.
Better climate data enables better triggers.
Better triggers enable more relevant insurance products.
Digital distribution can reduce the cost of reaching customers.
And automated payouts can accelerate financial recovery.
The Next Frontier: Making Climate Protection More Personalised
The next generation of parametric insurance is likely to become increasingly location-specific and data-driven.
Instead of using broad regional averages, products can incorporate increasingly granular information about:
- The insured person's location
- Local weather patterns
- Historical climate exposure
- Forecast conditions
- Occupation or livelihood
- Seasonal income patterns
- Specific climate hazards
This can enable products designed around the actual exposure of different customer groups.
A farmer may need protection against rainfall deficit.
A delivery worker may need protection against extreme heat.
A coastal small business may need protection against flooding.
A livestock owner may need protection against extreme temperature.
The underlying insurance architecture remains similar, but the climate trigger and product design can be tailored to the risk.
This is the direction in which climate resilience financing solutions are evolving: from generic insurance products toward targeted, data-driven financial protection.
Wrapping Up: A Shift That Is Already Under Way
The financial protection gap in emerging markets is not closing quickly enough through traditional mechanisms.
Microinsurance covered 344 million people globally in 2023, yet an 88% protection gap remained.
Parametric insurance does not solve that gap on its own.
But its ability to use objective climate triggers, automate payouts, reduce claims friction, and support low-ticket protection makes it one of the more promising mechanisms for expanding financial resilience among climate-exposed populations.
The bigger shift is from climate risk management to climate resilience.
Instead of asking only:
"What happens when a climate disaster occurs?"
financial institutions, insurers, employers, governments, and communities can increasingly ask:
"How quickly can we help people recover when it does?"
That is where parametric insurance can play a meaningful role.
Want to Explore Climate Resilience Solutions?
Climate risk is becoming an everyday financial risk for farmers, workers, and businesses across emerging markets.
Parametric insurance offers a practical way to convert measurable climate events into predefined financial protection—helping vulnerable communities access liquidity when they need it most.
Explore how climate intelligence, parametric insurance, and digital distribution can work together to build more resilient livelihoods and businesses.
00 Comments
Start the conversation
Be the first reader to share a thoughtful response.
Leave a Reply
Your email address will not be published. All comments are reviewed before appearing publicly.